Social Security Survivor Benefits 2027: Widow, Widower & Family Rules
Social Security Survivor Benefits 2027: Widow, Widower & Family Rules
Social Security survivor benefits in 2027 can provide monthly income to eligible widows, widowers, surviving divorced spouses, children and, in some cases, dependent parents after a worker dies.
The amount is not the same for every family.
According to the Social Security Administration, a surviving spouse may generally receive between 71.5% and 100% of the deceased spouse’s applicable benefit amount depending largely on the survivor’s age when benefits begin.
For 2027, survivor payments will also reflect the official 3.6% Social Security cost-of-living adjustment.
SSA estimates that an aged widow or widower living alone will receive an average of approximately:
$2,005 per month in January 2027
compared with:
$1,936 before the 2027 COLA.
For a widowed mother and two children, SSA estimates the average family benefit will rise from:
$3,932
to approximately:
$4,074 per month.
Those are national averages—not maximum survivor benefits.
Your actual payment depends on the deceased worker’s earnings record, when benefits are claimed and which family members qualify.
Here is how Social Security survivor benefits work in 2027.
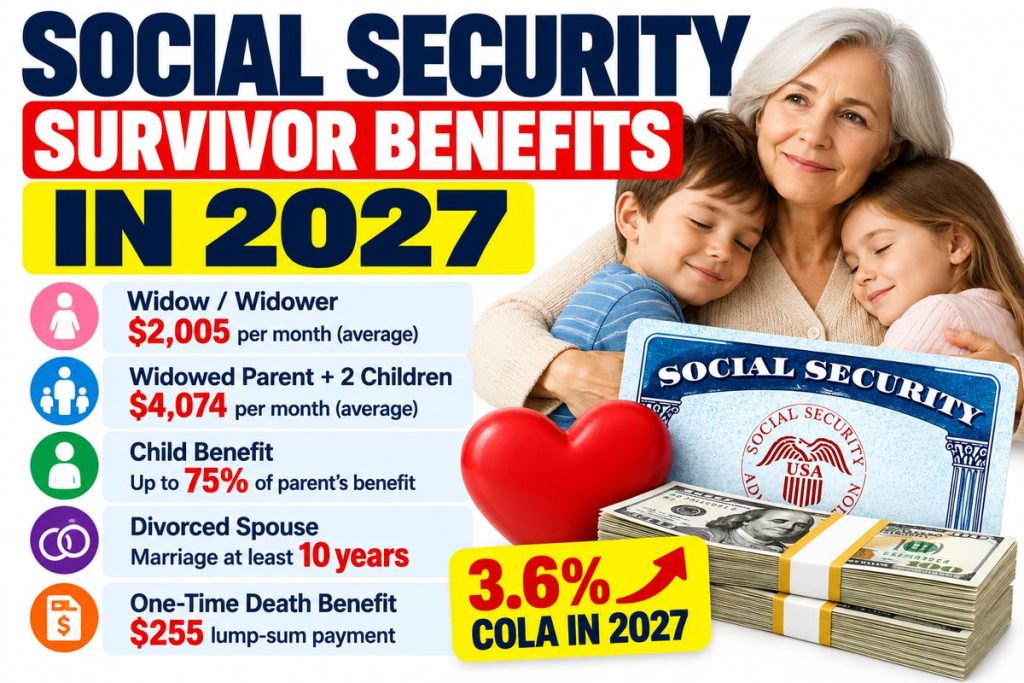
Social Security Survivor Benefits 2027 at a Glance
| Survivor situation | General rule |
|---|---|
| Surviving spouse age 60+ | May qualify for survivor benefits |
| Surviving spouse age 50–59 with disability | May qualify |
| Survivor at survivor full retirement age | Up to 100% of applicable deceased-worker benefit |
| Survivor claiming as early as age 60 | Benefit may begin around 71.5% |
| Surviving divorced spouse | Marriage generally must have lasted at least 10 years |
| Child | Generally up to 75% of parent’s benefit |
| Dependent parent | May qualify at age 62+ |
| One-time death payment | $255 for an eligible spouse or certain children |
| 2027 COLA | 3.6% |
| Average aged widow(er) alone in 2027 | About $2,005/month |
| Average widowed parent + 2 children | About $4,074/month |
These rules can become more complicated when the deceased worker claimed retirement early, delayed retirement, multiple family members qualify, or the surviving spouse also qualifies for their own retirement benefit.
How Much Are Social Security Survivor Benefits in 2027?
There is no single fixed survivor-benefit payment for 2027.
The payment is based primarily on the deceased worker’s Social Security record.
SSA states that surviving spouses and qualifying ex-spouses can receive an amount ranging from approximately:
71.5% to 100%
depending on when survivor benefits begin.
You can review SSA’s official explanation on its Survivor Benefit Amount page.
The maximum percentage for a surviving spouse is generally reached at the survivor’s applicable full retirement age for survivor benefits.
That age can be different from the full retirement age used for ordinary retirement benefits.
Average Widow and Widower Benefits After the 2027 COLA
SSA’s official 2027 COLA fact sheet estimates the average benefit for an:
aged widow or widower living alone
will rise from approximately:
$1,936 per month
to:
$2,005 per month.
That is an estimated increase of:
$2,005 − $1,936 = $69 per month.
Over 12 months:
$69 × 12 = $828
in additional annual benefits.
The estimated annual benefit at $2,005 per month would be:
$2,005 × 12 = $24,060.
Again, this is an average—not what every widow or widower receives.
You can see the full set of new amounts in our guide to the official 2027 Social Security COLA.
2027 Benefit for a Widowed Parent With Two Children
SSA also publishes an estimate for a household consisting of a widowed mother and two children.
Before the 2027 COLA, SSA estimates the average monthly family benefit at:
$3,932.
After the 3.6% COLA:
$4,074 per month.
Estimated increase:
$4,074 − $3,932 = $142 per month.
Over 12 months:
$142 × 12 = $1,704
in additional annual family benefits.
The annualized $4,074 monthly amount equals:
$48,888 per year.
Individual family payments can differ significantly because Social Security uses the deceased worker’s earnings record and family-benefit rules.
How Much Can a Widow or Widower Receive?
A surviving spouse’s payment depends heavily on age.
SSA says survivor benefits can generally begin at age:
60
for a surviving spouse without a qualifying disability.
A survivor with a qualifying disability may potentially begin benefits as early as:
age 50.
According to SSA, survivor payments can start at approximately 71.5% of the deceased spouse’s benefit and increase the longer the surviving spouse waits to claim.
At the survivor’s full retirement age, the payment can generally reach:
up to 100%.
SSA gives examples showing benefits rising above 75% around age 61, above 80% around age 63 and above 90% around age 65.
The exact percentage depends on the survivor’s age and applicable survivor full retirement age.
What Is Full Retirement Age for Survivor Benefits?
This is an important distinction.
Survivor full retirement age is not always the same as ordinary Social Security retirement full retirement age.
SSA says survivor FRA falls between:
age 66 and age 67
depending on the survivor’s date of birth.
You can check your precise survivor FRA using SSA’s Survivor Full Retirement Age tool.
For ordinary retirement benefits, full retirement age has reached 67 for people born in 1960 or later.
Our separate guide explains Social Security full retirement age in 2027 in detail.
Do not automatically assume your survivor FRA and retirement FRA are identical.
Can You Claim Survivor Benefits at Age 60?
Yes, in many cases.
A surviving spouse can generally begin survivor benefits at age 60.
However, starting early usually means accepting a permanently reduced survivor payment.
At the earliest ordinary survivor claiming age, SSA says the amount can begin at approximately:
71.5%
of the applicable deceased-worker benefit.
Waiting longer generally increases the survivor percentage until survivor full retirement age.
After survivor FRA, there is generally no additional survivor-benefit percentage for delaying the survivor claim simply because of age.
That differs from a worker’s own retirement benefit, which can continue increasing through delayed retirement credits until age 70.
Can a Disabled Widow or Widower Claim Before 60?
Potentially.
SSA states that a surviving spouse with a qualifying disability may be eligible for survivor benefits between:
ages 50 and 59.
Eligibility involves more than age alone, and Social Security’s disability rules apply.
Anyone considering disabled widow or widower benefits should verify eligibility directly with SSA because disability and survivor rules can interact.
Can You Receive Survivor Benefits While Caring for a Child?
Yes, under certain circumstances.
A surviving spouse may potentially qualify regardless of age when caring for the deceased worker’s qualifying child.
SSA specifically identifies situations involving a child who is:
under age 16
or:
has a qualifying disability
and is entitled on the deceased worker’s Social Security record.
These benefits are sometimes referred to as mother’s or father’s benefits.
Family-maximum rules may apply when several people receive benefits on the same worker’s record.
Social Security Survivor Benefits for Children in 2027
Children can also qualify for survivor benefits after a parent dies.
SSA says a child may generally qualify if unmarried and:
- age 17 or younger;
- age 18–19 and attending elementary or secondary school full time; or
- any age if the child developed a qualifying disability before age 22.
Certain stepchildren, adopted children, grandchildren and stepgrandchildren may also qualify under specific circumstances.
SSA states that eligible children generally receive:
75% of the deceased parent’s benefit amount
subject to the family maximum.
You can verify eligibility through SSA’s official Survivor Benefits Eligibility page.
What Is the Social Security Family Maximum?
When several family members qualify on the same worker’s Social Security record, there can be a limit on the total amount payable to the family.
This is known as the:
family maximum.
For example, suppose several children qualify for 75% of a deceased parent’s benefit.
Social Security does not necessarily pay every child an unrestricted 75% if the combined total exceeds the family maximum.
Instead, SSA may reduce qualifying family members’ payments so the total remains within the permitted family limit.
Importantly, SSA states that qualifying surviving divorced spouses generally do not count toward the family maximum in the same way.
Social Security Survivor Benefits for a Divorced Spouse
Divorce does not automatically eliminate survivor-benefit eligibility.
A surviving divorced spouse may qualify based on an ex-spouse’s Social Security record.
One of the major requirements is generally that the marriage lasted at least:
10 years.
SSA also generally requires the surviving divorced spouse to be:
age 60 or older
or:
age 50–59 with a qualifying disability.
A former spouse’s remarriage does not prevent an eligible surviving divorced spouse from claiming on that worker’s record.
Your own remarriage can matter.
SSA explains that remarriage before age 60 can generally affect survivor eligibility, while remarriage after age 60 does not necessarily prevent survivor benefits.
For comparison, ordinary spousal benefits while both spouses are living operate differently.
Read our detailed guide to Social Security spousal benefits in 2027 for those rules.
Does Claiming Survivor Benefits Affect an Ex-Spouse’s New Family?
Generally, a surviving divorced spouse’s benefit does not reduce the amount available to the deceased worker’s other qualifying family members through the ordinary family maximum calculation.
This is one reason survivor benefits for an ex-spouse should not be confused with splitting a fixed Social Security check among competing spouses.
Eligibility is determined under Social Security law based on the deceased worker’s record.
What if the Deceased Spouse Delayed Social Security Until Age 70?
Delayed retirement can be especially important for survivor benefits.
If a worker waits beyond full retirement age and earns delayed retirement credits, those credits can increase the amount used in calculating benefits for a surviving spouse or surviving divorced spouse.
In other words, delaying retirement can potentially provide:
a larger survivor benefit for a spouse later.
This differs from ordinary spousal benefits while the worker is alive.
A regular spouse benefit is generally based on the worker’s full-retirement-age amount rather than including delayed retirement credits.
Survivor benefits can incorporate those delayed credits.
This distinction can be important for married couples deciding when the higher-earning spouse should claim Social Security.
What if the Deceased Worker Claimed Social Security Early?
Early retirement can also affect survivor benefits.
If the deceased worker began Social Security before full retirement age, special widow or widower benefit limits can apply.
This means it is not always correct to assume that a surviving spouse who waits until survivor FRA automatically receives the deceased worker’s unreduced Primary Insurance Amount.
SSA applies specific rules when the deceased worker received reduced retirement benefits before death.
Because these calculations can become complex, surviving spouses should request an individualized benefit calculation from Social Security rather than relying only on percentage examples.
Can You Receive Your Own Social Security and Survivor Benefits?
You generally do not simply add two full Social Security benefits together.
If you qualify for both:
- your own retirement benefit; and
- survivor benefits;
SSA generally pays according to rules designed to provide the higher applicable amount rather than two full checks added together.
However, survivor benefits have an important planning feature.
SSA says you may be able to:
start survivor benefits first and switch to your own retirement benefit later
if your own benefit will eventually become larger.
For example, a person might receive survivor benefits while allowing their own retirement benefit to grow until age 70.
Alternatively, in some situations a person could begin their own reduced retirement benefit first and later switch to a larger survivor benefit.
This flexibility is one of the biggest differences between survivor benefits and ordinary spousal benefits.
SSA recommends discussing the options with a representative before deciding which benefit to claim first.
Example: Survivor Benefit First, Retirement Benefit Later
Suppose a widow qualifies for:
$1,800 per month in survivor benefits
and has her own retirement benefit that could grow to:
$2,400 per month at age 70.
Depending on her exact eligibility and claiming circumstances, she might be able to collect the survivor benefit first and switch to her own larger retirement benefit later.
The two full amounts would not be paid together.
The objective would be to use the benefit that produces the better payment at each stage, subject to SSA rules.
Individual calculations can differ, so this example is only illustrative.
Does Working Reduce Survivor Benefits?
It can if you are below the applicable full retirement age.
SSA’s retirement earnings test can apply to survivor beneficiaries who work while under full retirement age.
For 2027, SSA has officially increased the general earnings-test limit for workers under full retirement age for the full year to:
$25,560.
That equals:
$2,130 per month
under the monthly figure published by SSA.
Above the annual limit, Social Security generally withholds:
$1 in benefits for every $2 earned above the limit.
For someone reaching full retirement age during 2027, the higher earnings limit is:
$67,920
or:
$5,660 per month
for applicable months before full retirement age.
Under that rule, SSA generally withholds:
$1 for every $3 above the limit.
Beginning with the month full retirement age is reached, the retirement earnings test no longer applies.
These are withholding rules—not necessarily permanent dollar-for-dollar benefit losses.
Do Survivor Benefits Get the 2027 COLA?
Yes.
Social Security survivor benefits are part of the Old-Age, Survivors, and Disability Insurance program and receive the annual Social Security COLA.
For 2027, the official increase is:
3.6%.
SSA announced that the adjustment applies beginning with benefits payable for January 2027.
If you already receive survivor benefits, your personalized payment information should appear in your Social Security COLA notice.
See our guide to the 2027 Social Security COLA notice for details about when individualized notices become available.
When Will 2027 Survivor Benefits Be Paid?
Survivor benefits follow Social Security’s regular payment calendar.
For many beneficiaries who began receiving benefits after May 1997, payment timing is generally linked to the beneficiary’s birthday.
Payments commonly occur on the:
second Wednesday
third Wednesday
or:
fourth Wednesday
of the month.
Different rules apply to some beneficiaries who started Social Security before May 1997 and to people who receive both Social Security and SSI.
Our 2027 Social Security payment schedule provides the complete calendar.
Is There a $255 Social Security Death Benefit in 2027?
Yes.
Social Security can pay a separate one-time:
$255 lump-sum death payment
to an eligible surviving spouse or, in some situations, qualifying children.
This is different from monthly survivor benefits.
It is not $255 per month.
It is:
a one-time payment.
SSA says eligible survivors must apply for the lump-sum death payment within:
two years of the worker’s death.
You can review the official requirements on SSA’s Lump-Sum Death Payment page.
Do You Automatically Receive the $255 Death Payment?
Not necessarily.
Someone must meet SSA’s eligibility rules.
A spouse may qualify, and if there is no eligible spouse, certain children may qualify.
The safest approach after a spouse or parent dies is to contact Social Security promptly and ask about both:
monthly survivor benefits
and:
the $255 lump-sum death payment.
Can You Apply for Survivor Benefits Online?
According to SSA, monthly survivor-benefit applications are not currently completed online.
To apply, SSA instructs survivors to contact Social Security.
The main SSA phone number is:
1-800-772-1213
TTY:
1-800-325-0778
SSA says representatives are generally available Monday through Friday from 8 a.m. to 7 p.m. local time.
You can also contact a local Social Security office.
SSA’s official eligibility and application information is available at:
What Documents Might Social Security Ask For?
SSA may request documents or information such as:
- proof of the worker’s death;
- your birth certificate or other proof of birth;
- marriage information;
- divorce documents when applicable;
- Social Security numbers;
- proof of citizenship or lawful status when required;
- children’s birth information;
- tax or earnings information; and
- other documents relevant to eligibility.
Not every applicant will need every document.
SSA recommends contacting the agency rather than delaying an application simply because you do not currently have every record available.
What Happens if You Already Receive Spousal Benefits When Your Spouse Dies?
SSA says people already receiving spouse benefits on the deceased worker’s record are generally converted to survivor benefits after Social Security receives notice of the death.
However, you should still contact SSA.
You may need to discuss:
- the survivor benefit amount;
- the $255 death payment;
- your own retirement-benefit options;
- Medicare deductions; and
- whether another claiming strategy could produce a higher future payment.
Does Medicare Continue After a Spouse Dies?
Medicare eligibility is separate from simply receiving a deceased spouse’s Social Security check.
SSA states that a survivor may potentially qualify for Medicare based on a deceased family member’s work history if the survivor is:
65 or older
or qualifies through certain disability or end-stage renal disease rules.
A spouse’s death does not automatically mean the surviving spouse loses Medicare.
Individual situations can differ, so anyone concerned about coverage should verify their record with Social Security and Medicare.
Survivor Benefits vs. Spousal Benefits: What’s the Difference?
These two programs are often confused.
Spousal benefit
Paid while the worker is alive.
The maximum regular spouse benefit is generally up to:
50% of the worker’s full-retirement-age amount
when claimed at the spouse’s full retirement age.
Survivor benefit
Paid after the worker dies.
A surviving spouse can potentially receive:
up to 100% of the applicable deceased-worker benefit
at survivor full retirement age.
Another major difference involves delayed retirement credits.
A regular spouse generally does not receive the worker’s delayed retirement credits as part of the maximum spouse benefit.
A surviving spouse can benefit from delayed retirement credits the deceased worker earned.
That distinction can make survivor planning particularly important for married couples.
Does a Widow Get 100% of Her Husband’s Social Security?
Potentially, but not automatically in every situation.
A surviving spouse who reaches the applicable survivor full retirement age can generally receive up to 100% of the applicable deceased-worker benefit.
However, the actual amount can be affected by:
- the survivor’s claiming age;
- whether the deceased worker claimed early;
- delayed retirement credits;
- the survivor’s own Social Security benefit;
- family maximum rules;
- earnings-test withholding; and
- other Social Security provisions.
The deceased spouse’s bank-deposit amount should therefore not automatically be treated as the guaranteed future survivor payment.
Does a Husband Get Survivor Benefits From His Wife?
Yes.
Social Security survivor rules apply to qualifying surviving husbands as well as wives.
A widower who satisfies the eligibility rules may qualify based on his deceased wife’s work record.
The same basic age rules apply.
Can an Ex-Spouse Get Survivor Benefits if the Deceased Remarried?
Yes, potentially.
A surviving divorced spouse can qualify even if the deceased former spouse later remarried.
The deceased worker’s new spouse may also qualify separately.
An eligible surviving divorced spouse does not generally reduce benefits payable to the current surviving spouse through the ordinary family maximum.
Frequently Asked Questions
How much are Social Security survivor benefits in 2027?
There is no fixed payment for everyone.
SSA says surviving spouses can generally receive between 71.5% and 100% of the deceased spouse’s applicable benefit depending largely on claiming age and individual circumstances.
What is the average widow benefit in 2027?
SSA estimates an aged widow or widower living alone will receive approximately $2,005 per month after the 3.6% COLA.
How much does a widowed parent with two children receive in 2027?
SSA estimates the average benefit for a widowed mother and two children at approximately $4,074 per month after the 2027 COLA.
What age can a widow start Social Security survivor benefits?
A surviving spouse can generally begin survivor benefits at age 60.
Can a disabled widow claim earlier?
Potentially. SSA says qualifying disabled surviving spouses may become eligible beginning at age 50.
Does a widow receive 100% of her husband’s Social Security?
A surviving spouse can potentially receive up to 100% at survivor full retirement age, but individual calculations can differ.
Can a divorced spouse receive survivor benefits?
Yes. A surviving divorced spouse may qualify if the marriage generally lasted at least 10 years and other requirements are met.
Can children receive Social Security when a parent dies?
Yes. Qualifying children generally receive up to 75% of the deceased parent’s benefit, subject to family maximum rules.
Do survivor benefits increase by 3.6% in 2027?
Eligible Social Security survivor benefits receive the official 3.6% 2027 COLA.
Can I get survivor benefits and my own retirement benefit at the same time?
You generally do not receive two full benefits added together. SSA pays according to applicable dual-entitlement rules, but survivors may have options to start one type of benefit and switch to another later.
Can I start survivor benefits and switch to my own Social Security at 70?
Potentially, yes. SSA specifically notes that some people can start survivor benefits and later switch to their own higher retirement benefit.
Is there still a $255 Social Security death benefit in 2027?
Yes. An eligible spouse or certain children may receive a one-time $255 lump-sum death payment.
Can I apply for survivor benefits online?
SSA says monthly survivor-benefit applications are not currently available entirely online. Contact Social Security by phone or through a local office.
Bottom Line
Social Security survivor benefits in 2027 can provide important income after a worker dies.
A surviving spouse can generally receive:
71.5% to 100%
of the applicable deceased-worker benefit depending largely on claiming age.
For 2027, SSA estimates:
$2,005 per month for an aged widow or widower living alone;
and:
$4,074 per month for a widowed parent with two children.
Children may generally receive:
75% of the deceased parent’s benefit
subject to family maximum rules.
A surviving divorced spouse may also qualify when the marriage generally lasted at least:
10 years.
And an eligible spouse or child may receive the separate:
$255 one-time death payment.
Perhaps the most important planning point is that survivor benefits operate differently from ordinary spousal benefits.
A surviving spouse may sometimes start survivor benefits first and later switch to their own larger retirement benefit—or use the opposite strategy when appropriate.
Because early claiming, delayed retirement credits, divorce, remarriage and family maximum rules can change the calculation, anyone facing a spouse’s death should contact Social Security for an individualized estimate before making a claiming decision.