Social Security Full Retirement Age in 2027: Age 67 Rules Explained
Social Security Full Retirement Age in 2027: Age 67 Rules Explained
One of the most important Social Security milestones arrives in 2027 for people born in 1960.
For most people born in 1960, Social Security’s full retirement age is:
67
That means they reach full retirement age during 2027.
Full retirement age—or FRA—is the age when you can receive your full unreduced Social Security retirement benefit based on your earnings record.
You can still claim retirement benefits before age 67.
Social Security retirement benefits can begin as early as:
age 62
But claiming at 62 can reduce the monthly benefit by as much as:
30%
for someone whose full retirement age is 67.
You can also delay Social Security after full retirement age.
For someone with an FRA of 67, waiting until:
age 70
can increase the retirement benefit to approximately:
124% of the full-retirement-age amount
Here is how the 2027 retirement-age rules work, how much early claiming can reduce benefits and what delaying until 70 can mean for your monthly payment.
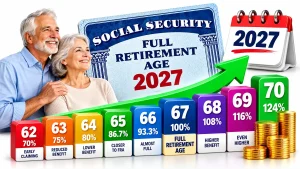
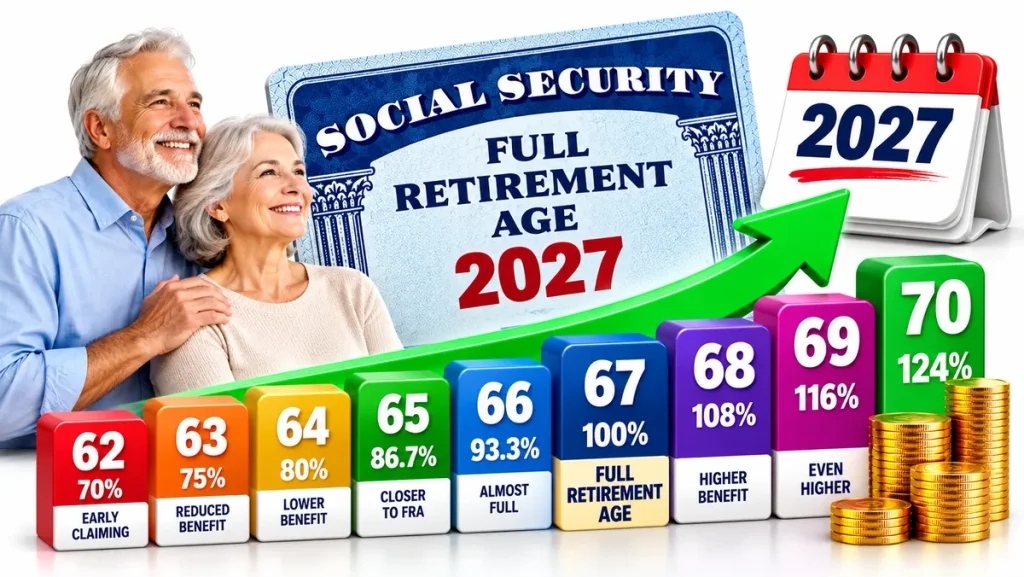
Social Security Retirement Ages in 2027 at a Glance
| Claiming age | Approx. worker benefit if FRA is 67 |
|---|---|
| 62 | 70% |
| 63 | 75% |
| 64 | 80% |
| 65 | 86.7% |
| 66 | 93.3% |
| 67 | 100% |
| 68 | 108% |
| 69 | 116% |
| 70 | 124% |
These percentages illustrate how claiming age can affect a worker with a full retirement age of 67.
Your actual Social Security payment depends on your earnings history and personal benefit calculation.
What Is Full Retirement Age in 2027?
For people born in:
1960 or later
Social Security retirement full retirement age is:
67
This is the maximum full-retirement-age level established under current law for retirement benefits.
People born before 1960 can have an earlier FRA.
For example:
| Birth year | Full retirement age |
|---|---|
| 1955 | 66 and 2 months |
| 1956 | 66 and 4 months |
| 1957 | 66 and 6 months |
| 1958 | 66 and 8 months |
| 1959 | 66 and 10 months |
| 1960 or later | 67 |
For most people born during 1960, their 67th birthday falls during 2027.
Official SSA guidance:
Important Exception for January 1 Birthdays
Social Security has a special rule for birthdays that fall on the:
first day of a month
SSA says that if your birthday is January 1, your benefit-age calculation generally uses the previous year.
This means someone born on:
January 1, 1960
should not simply assume the same timing as someone born later in 1960.
SSA instructs people with a January 1 birthday to use the previous year when determining retirement age.
For everyone close to an age boundary, verify the exact date through SSA’s:
What Does “Full Retirement Age” Actually Mean?
Full retirement age does not mean:
- the earliest age you can retire;
- the age when you must stop working;
- the age when you must claim Social Security; or
- the age when Medicare begins.
Instead, FRA is primarily the age when you become eligible for:
100% of your calculated primary retirement benefit
without an early-retirement reduction.
For people born in 1960 or later:
FRA = 67
You can claim before 67 and receive less.
You can delay after 67 and receive more.
Can You Claim Social Security at 62 in 2027?
Yes.
The earliest standard age for Social Security retirement benefits remains:
62
But if your FRA is 67 and you start at 62, you are claiming:
60 months early
Social Security permanently reduces your monthly benefit for starting early.
For someone with FRA 67, SSA shows that starting at exactly age 62 produces approximately:
70% of the full retirement benefit
That is effectively a:
30% reduction
from the amount payable at FRA.
Example: $2,000 Full Retirement Benefit
Suppose your benefit at age 67 would be:
$2,000 per month
If you claim at 62:
$2,000 × 70% = $1,400
Approximate monthly benefit:
$1,400
Monthly difference:
$2,000 − $1,400 = $600
Annual difference:
$600 × 12 = $7,200
The trade-off is that the person who claims at 62 begins receiving benefits five years earlier.
That is why claiming decisions cannot be evaluated by monthly benefit alone.
How Social Security Calculates the Early-Retirement Reduction
For retirement benefits, SSA generally reduces your payment by:
5/9 of 1% for each of the first 36 months
you claim before full retirement age.
If you claim more than 36 months early, the remaining months are generally reduced by:
5/12 of 1% per month
For someone with FRA 67 who claims exactly at 62:
First 36 months:
36 × 5/9 of 1% = 20%
Remaining 24 months:
24 × 5/12 of 1% = 10%
Total reduction:
20% + 10% = 30%
Therefore:
100% − 30% = 70%
of the full benefit.
Claiming at 63
SSA’s chart for people born in 1960 or later shows a worker claiming at exactly age 63 receives approximately:
75% of the full benefit
Using a $2,000 FRA benefit:
$2,000 × 75% = $1,500
Monthly reduction versus FRA:
$500
Claiming at 64
At age 64, the worker benefit is approximately:
80%
For a $2,000 full benefit:
$2,000 × 80% = $1,600
Claiming at 65
At age 65, SSA’s table shows approximately:
86.7%
of the full worker benefit.
Using the same example:
$2,000 × 86.7% ≈ $1,734
This also highlights an important point:
Medicare eligibility and Social Security full retirement age are not the same thing.
Medicare eligibility generally begins at:
65
while Social Security FRA for people born in 1960 or later is:
67
Claiming at 66
At age 66, someone with FRA 67 receives approximately:
93.3%
of the full benefit.
Example:
$2,000 × 93.3% ≈ $1,866
Waiting the final year until 67 eliminates the remaining early-retirement reduction.
Claiming at 67
At full retirement age:
100%
of the calculated retirement benefit is payable.
Example:
$2,000 × 100% = $2,000
For people born in 1960 or later, 67 is the point where the early-claiming reduction disappears.
But it is not necessarily the maximum monthly benefit available.
What Happens if You Wait Past Age 67?
Social Security provides:
delayed retirement credits
for eligible workers who postpone claiming after full retirement age.
For people born in 1943 or later, delayed retirement credits increase the benefit at an annual rate of:
8%
until age:
70
For someone with an FRA of 67:
Claim at 68
Approximately:
108%
Claim at 69
Approximately:
116%
Claim at 70
Approximately:
124%
Delaying beyond age 70 does not continue increasing the retirement benefit through delayed retirement credits.
Example: Waiting Until Age 70
Assume your full benefit at age 67 is:
$2,000
If you wait until age 70:
$2,000 × 124% = $2,480
Difference compared with claiming at 67:
$2,480 − $2,000 = $480 per month
Difference compared with claiming at 62:
$2,480 − $1,400 = $1,080 per month
That is a substantial difference in monthly income.
But the person waiting until 70 also gives up years of earlier payments.
Age 62 vs. 67 vs. 70 Example
Assume a hypothetical full-retirement-age benefit of:
$2,000 per month
| Claiming age | Approx. monthly benefit | Percentage of FRA amount |
|---|---|---|
| 62 | $1,400 | 70% |
| 67 | $2,000 | 100% |
| 70 | $2,480 | 124% |
This comparison does not include future COLAs.
COLAs can apply after a person becomes eligible and are reflected under Social Security’s rules, so actual future nominal payments can differ from this simplified comparison.
Is 67 the New Mandatory Retirement Age?
No.
There is no general Social Security rule requiring you to stop working at age:
67
Full retirement age is a Social Security benefit concept.
You can:
- continue working;
- retire earlier;
- retire later;
- claim benefits before FRA; or
- delay Social Security until 70.
Your employer’s retirement policies, pensions and personal financial circumstances are separate matters.
Can You Work After Full Retirement Age?
Yes.
And one major Social Security rule changes once you reach FRA.
Before full retirement age, people who claim Social Security and continue working can be affected by the:
retirement earnings test
After reaching full retirement age:
the retirement earnings test no longer applies.
There is no earnings-test withholding based on wages beginning with the month you reach FRA.
For the projected 2027 limits before FRA, read our 2027 Social Security Earnings Limit guide.
Example: Working at Age 68
Suppose you are:
68
and receive Social Security retirement benefits while earning:
$100,000 per year from work
Because you are above full retirement age, there is:
no retirement earnings-test limit
Your wages could still affect other issues such as:
- federal income taxes;
- payroll taxes;
- Medicare IRMAA in later years; and
- your Social Security benefit calculation if new earnings replace lower years.
But the retirement earnings test itself does not reduce your benefit after FRA.
What if You Work Before Age 67?
If you claim benefits before FRA and continue working, an annual earnings limit may apply.
SSA can temporarily withhold benefits when earnings exceed the applicable exempt amount.
The rules differ depending on whether you:
- remain below FRA for the entire year; or
- reach FRA during that year.
Our detailed 2027 Social Security Earnings Limit guide explains those rules and projected 2027 limits.
Are Benefits Withheld for Work Permanently Lost?
Not necessarily.
SSA explains that when a beneficiary reaches full retirement age, it recalculates the retirement benefit to account for months when benefits were withheld because of excess earnings.
This means the retirement earnings test should not simply be viewed as a permanent dollar-for-dollar loss.
The calculation can increase future monthly benefits after FRA.
Does Working After 67 Increase Your Social Security Benefit?
It can.
Social Security retirement benefits are generally based on your:
35 highest years of indexed earnings
If you continue working and your new earnings replace a lower year among those used in your benefit calculation, SSA can recalculate your benefit.
So working after FRA can potentially increase your benefit independently of delayed retirement credits.
Do You Need 40 Work Credits Before Age 67?
Most workers need:
40 Social Security credits
to qualify for retirement benefits.
Because workers can earn up to four credits per year, 40 credits generally represents approximately:
10 years of covered work
But having 40 credits only establishes basic eligibility.
It does not guarantee a particular monthly amount.
For more detail, see our 2027 Social Security Work Credits guide.
Does the Social Security Taxable Maximum Affect FRA?
No.
The taxable maximum and full retirement age are different Social Security rules.
The taxable maximum determines how much annual covered earnings are subject to Social Security payroll tax.
The Trustees currently project a 2027 wage base of:
$190,200
but that figure is not final yet.
Read our 2027 Social Security Taxable Maximum guide.
Full retirement age, by contrast, is determined by your:
year of birth
not your income.
Does the 2027 COLA Change Full Retirement Age?
No.
Social Security COLA and full retirement age are separate.
The COLA changes benefit amounts based primarily on inflation.
It does not change your statutory FRA.
Someone whose retirement FRA is 67 will not suddenly have an FRA of 67 and 3 months because inflation increases.
The age schedule is set under federal law.
For the latest benefit-increase calculation, use our Social Security COLA 2027 Calculator.
What Is the Best Age to Claim Social Security?
There is no one age that is best for everyone.
Important factors include:
- health;
- expected longevity;
- employment income;
- savings;
- pensions;
- spouse benefits;
- survivor-benefit needs;
- taxes;
- debt;
- monthly spending needs; and
- whether you can afford to delay.
Claiming early provides income sooner.
Waiting provides a larger monthly retirement benefit.
Neither factor alone determines the correct decision.
When Claiming at 62 May Make Sense
Some people may consider earlier claiming when:
- they stop working;
- they need income;
- they have significant health concerns;
- they have limited other retirement assets; or
- their household claiming strategy supports an earlier start.
The trade-off is a permanently lower monthly retirement benefit than if they waited to FRA.
When Waiting Until 67 May Make Sense
Waiting until FRA avoids the early-retirement reduction.
It can be attractive for someone who:
- continues working;
- has sufficient savings;
- wants a larger guaranteed monthly payment;
- does not need benefits immediately; or
- wants to avoid the retirement earnings test.
When Waiting Until 70 May Make Sense
Waiting until 70 can provide the highest monthly retirement benefit available through delayed retirement credits.
This can be especially relevant for:
- healthy individuals expecting a long retirement;
- higher earners;
- households concerned about survivor income; and
- people with enough income or savings to delay.
But delaying is not automatically optimal for every person.
Why Claiming Age Matters for Survivor Benefits
A worker’s claiming decision can affect household retirement planning.
Higher worker retirement benefits resulting from delayed retirement may affect the amount potentially available to a surviving spouse under Social Security’s survivor rules.
Survivor benefits have their own claiming ages and calculations, so couples should consider more than each person’s individual retirement check.
Spousal Benefits and FRA
Spousal benefits also have early-claiming reductions.
For someone whose retirement FRA is 67, SSA’s chart shows a spouse who claims at age 62 may receive approximately:
32.5% of the worker’s full retirement benefit
rather than the maximum spousal amount of up to:
50%
at full retirement age.
Spousal benefit rules can be complicated and depend on eligibility circumstances.
Medicare Still Starts Around Age 65
One common mistake is assuming that because Social Security FRA is 67, Medicare should also be delayed until 67.
That is incorrect.
Medicare eligibility generally remains:
age 65
under current law.
If you delay Social Security, you may still need to take separate action to enroll in Medicare.
Missing Medicare enrollment deadlines can create late-enrollment penalties in some circumstances.
Should You Claim Social Security When You Enroll in Medicare?
Not necessarily.
Social Security and Medicare can start at different ages.
Someone may:
enroll in Medicare at 65
and:
wait until 67 or 70 to claim Social Security
depending on their circumstances.
If you receive Social Security before 65, Medicare enrollment can work differently because SSA may automatically enroll eligible beneficiaries in certain Medicare coverage.
What Happens to Full Retirement Age After 2027?
Under current law, full retirement age remains:
67
for people born in 1960 or later.
It does not continue automatically rising to 68.
Proposals to change Social Security retirement ages are sometimes discussed, but proposed changes are not the same thing as enacted law.
For current planning, SSA’s official rule remains:
67 for people born in 1960 or later.
Frequently Asked Questions
What is the Social Security full retirement age in 2027?
For people born in 1960 or later, retirement full retirement age is 67.
Who turns full retirement age in 2027?
Most people born in 1960 reach age 67 during 2027. SSA has special rules for birthdays on the first day of a month, so verify your exact date with SSA.
Can I collect Social Security at 62?
Yes.
Retirement benefits can generally begin at age 62, but the monthly amount is permanently reduced when claimed before FRA.
How much do I lose if I claim at 62 instead of 67?
For someone with a full retirement age of 67, claiming at exactly 62 generally reduces the worker benefit by 30%, leaving approximately 70% of the FRA amount.
How much do I get at age 67?
At FRA, you generally receive 100% of your calculated full retirement benefit.
How much more do I get if I wait until age 70?
For someone born in 1960 or later, waiting from FRA 67 until age 70 generally produces approximately 124% of the FRA retirement benefit through delayed retirement credits.
Do benefits keep increasing if I wait after 70?
Delayed retirement credits stop at age 70.
Can I work after age 67 without losing Social Security benefits?
The retirement earnings test no longer applies beginning with the month you reach full retirement age.
Does Medicare start at 67 now?
No.
Medicare eligibility generally remains at age 65.
Does COLA change my full retirement age?
No.
COLA changes benefit amounts, not the statutory retirement-age schedule.
Is full retirement age going to 68 in 2027?
Not under current law.
SSA currently lists FRA as 67 for people born in 1960 or later.
Bottom Line
For most people born in 1960, 2027 is the year they reach Social Security full retirement age.
The key age is:
67
At that point, a worker can generally receive:
100% of their calculated full retirement benefit
and the Social Security retirement earnings test no longer applies.
Claiming earlier can reduce the monthly benefit.
For someone with FRA 67:
Age 62 ≈ 70%
Age 63 ≈ 75%
Age 64 ≈ 80%
Age 65 ≈ 86.7%
Age 66 ≈ 93.3%
Age 67 = 100%
Waiting beyond FRA can increase the payment through delayed retirement credits:
Age 68 ≈ 108%
Age 69 ≈ 116%
Age 70 ≈ 124%
The best claiming age depends on your health, finances, employment, spouse and retirement goals.
But the rule itself is already established:
Social Security full retirement age is 67 for people born in 1960 or later.
Related Reading on Elite Era Trends
2027 Retirement Guide: Social Security, Medicare, COLA & Major Changes
2027 Social Security Earnings Limit: Projected Limits Explained
2027 Social Security Work Credits
2027 Social Security Taxable Maximum
2027 Social Security Benefit Changes: COLA, Retirement Age & New Limits