How Much Can You Earn While Collecting Social Security in 2027? New $25,560 Limit Explained
How Much Can You Earn While Collecting Social Security in 2027?
If you collect Social Security retirement benefits while continuing to work in 2027, there is an important new number to know:
$25,560.
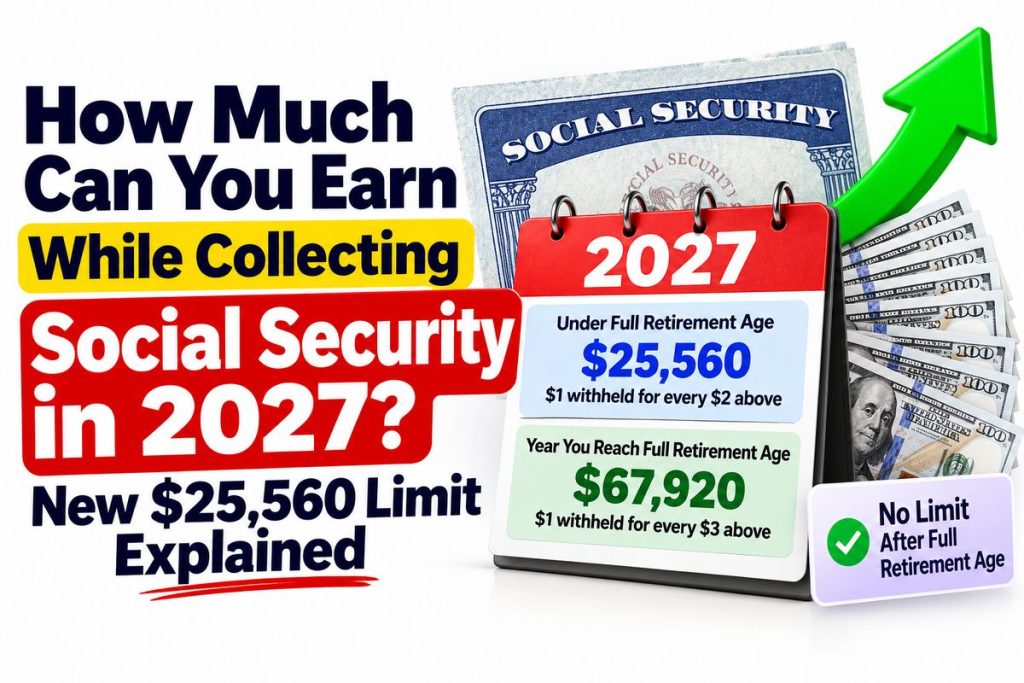
That is the official 2027 Social Security earnings limit for someone who remains below full retirement age for the entire year.
The Social Security Administration has also confirmed a much higher limit of:
$67,920
for people who reach full retirement age during 2027.
And once you reach full retirement age, the rule changes completely:
There is no Social Security retirement earnings limit beginning with the month you reach full retirement age.
That does not mean you are prohibited from earning more than $25,560 or $67,920.
You can earn more.
Instead, Social Security may temporarily withhold part of your retirement benefits when your earnings exceed the applicable limit.
Here is exactly how the 2027 Social Security earnings test works, how much may be withheld at different income levels, what income counts, what does not count, and what happens to benefits that Social Security withholds.
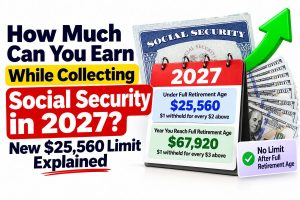
2027 Social Security Earnings Limits at a Glance
| Your situation in 2027 | Earnings limit | Withholding rule |
|---|---|---|
| Under full retirement age for all of 2027 | $25,560 | $1 withheld for every $2 above the limit |
| Reach full retirement age during 2027 | $67,920 | $1 withheld for every $3 above the limit before FRA |
| At full retirement age | No limit | No retirement earnings-test withholding |
The Social Security Administration also lists monthly equivalents of:
$2,130 per month
for the lower earnings-test amount, and:
$5,660 per month
for the higher amount applicable in the year full retirement age is reached.
The annual limits are the numbers most workers will use.
What Is the 2027 Social Security Earnings Limit?
The Social Security retirement earnings test applies when you:
- are receiving Social Security retirement benefits;
- continue to work; and
- have not yet reached full retirement age.
For 2027, the standard annual earnings limit rises to:
$25,560.
In 2026, the limit was:
$24,480.
That means the annual limit increases by:
$1,080
for 2027.
If you remain under full retirement age for the entire year and earn more than $25,560, Social Security generally withholds:
$1 in benefits for every $2 earned above $25,560.
Can You Earn More Than $25,560 While Collecting Social Security?
Yes.
This is one of the biggest misconceptions about the Social Security earnings test.
The $25,560 number is not a maximum amount you are legally allowed to earn.
You can earn:
$30,000
$50,000
$75,000
or substantially more.
The issue is that Social Security may temporarily withhold part or all of your retirement benefits when your earnings exceed the applicable limit.
Your employer does not have to stop paying you.
You do not lose your eligibility to work.
And exceeding the limit does not automatically cancel Social Security permanently.
Instead, SSA calculates how much of your benefit should be withheld.
How Much Does Social Security Withhold in 2027?
If you are under full retirement age for the entire year:
$1 is withheld for every $2 you earn above $25,560.
The basic calculation is:
Annual earnings − $25,560 = excess earnings
Then:
Excess earnings ÷ 2 = approximate amount withheld
Here are several examples.
Example: You Earn $30,000 in 2027
Suppose you are receiving retirement benefits and remain below full retirement age throughout 2027.
Your wages are:
$30,000
2027 earnings limit:
$25,560
Excess earnings:
$30,000 − $25,560 = $4,440
Social Security generally withholds $1 for every $2 above the limit:
$4,440 ÷ 2 = $2,220
Approximate Social Security benefits withheld:
$2,220
Example: You Earn $40,000
Annual earnings:
$40,000
Subtract the $25,560 limit:
$40,000 − $25,560 = $14,440
Divide by two:
$14,440 ÷ 2 = $7,220
Approximate benefits withheld:
$7,220
Example: You Earn $50,000
Annual earnings:
$50,000
Excess:
$50,000 − $25,560 = $24,440
Benefits potentially withheld:
$24,440 ÷ 2 = $12,220
Example: You Earn $75,000
Annual earnings:
$75,000
Excess earnings:
$75,000 − $25,560 = $49,440
Approximate amount withheld:
$49,440 ÷ 2 = $24,720
If your annual Social Security benefit is less than the calculated amount that needs to be withheld, SSA could withhold all of your scheduled benefits for part or potentially all of the applicable period.
That does not necessarily mean those benefits disappear permanently.
More on that below.
2027 Earnings-Test Examples
| Your 2027 earnings | Amount over $25,560 | Approx. benefit withheld |
|---|---|---|
| $25,560 | $0 | $0 |
| $30,000 | $4,440 | $2,220 |
| $40,000 | $14,440 | $7,220 |
| $50,000 | $24,440 | $12,220 |
| $75,000 | $49,440 | $24,720 |
These examples assume you remain below full retirement age throughout 2027.
The rule is different if you reach full retirement age during the year.
What If You Reach Full Retirement Age in 2027?
Social Security gives you a much higher earnings limit during the calendar year in which you reach full retirement age.
The official 2027 limit is:
$67,920.
And the withholding rate becomes more favorable.
Instead of withholding $1 for every $2 above the limit, SSA generally withholds:
$1 for every $3 above $67,920.
There is another important advantage:
SSA counts only your earnings before the month you reach full retirement age.
Earnings from the month you reach FRA forward do not count toward the retirement earnings test.
Example: You Reach Full Retirement Age in August 2027
Suppose you reach full retirement age in:
August 2027
and earn:
$72,000
from January through July.
The special 2027 FRA-year limit is:
$67,920
Excess earnings before FRA:
$72,000 − $67,920 = $4,080
SSA withholds $1 for every $3 over the limit:
$4,080 ÷ 3 = $1,360
Approximate amount withheld:
$1,360
Beginning in August—the month you reach full retirement age—the retirement earnings test no longer applies.
You can earn any amount after that without having Social Security benefits withheld because of the retirement earnings test.
What If You Earn $100,000 but Only $60,000 Before FRA?
This demonstrates why the FRA-year rule is so important.
Suppose you reach full retirement age in August.
You earn:
$60,000 from January through July
and another:
$40,000 from August through December.
Total 2027 wages:
$100,000
But for the special earnings test, only the earnings before your FRA month count.
Those earnings are:
$60,000
That is below the 2027 higher limit of:
$67,920.
Therefore, the $40,000 earned from August through December does not cause retirement earnings-test withholding.
What Happens Once You Reach Full Retirement Age?
Beginning with the month you reach full retirement age:
there is no earnings limit.
You can continue working and earn:
$50,000
$100,000
$250,000
or more without losing Social Security retirement benefits because of the retirement earnings test.
Your wages can still affect other financial matters.
For example, earnings may affect:
- federal and state income taxes;
- Social Security payroll taxes;
- Medicare taxes;
- future Medicare IRMAA calculations;
- the taxation of Social Security benefits.
But the retirement earnings test itself disappears beginning with your FRA month.
For most people born in 1960 or later, full retirement age is:
67.
For more detail, see our guide to Social Security Full Retirement Age in 2027.
Are Benefits Withheld Because of Work Lost Forever?
Not necessarily.
This is one of the most important parts of the earnings test.
SSA explains that benefits withheld because of excess earnings are not simply treated as permanently lost payments.
When you reach full retirement age, Social Security recalculates your monthly retirement benefit to account for months when benefits were withheld because of the earnings test.
That can result in a:
higher monthly Social Security benefit after FRA.
However, this does not generally mean SSA sends you a lump-sum refund for every dollar previously withheld.
Instead, SSA adjusts your benefit calculation going forward.
Simple Example of Withheld Benefits
Suppose you claimed Social Security before FRA.
Because you continued working, SSA withheld several full monthly checks.
When you eventually reach FRA, SSA reviews the months for which benefits were withheld due to excess earnings.
Your early-retirement reduction can then be adjusted to reflect those months.
The result can be a permanently higher monthly benefit than you otherwise would have received.
That is why describing earnings-test withholding as Social Security simply “taking away” your money can be misleading.
What Income Counts Toward the Social Security Earnings Limit?
For the retirement earnings test, SSA generally counts income from work.
That includes:
Wages from a job
and:
Net earnings from self-employment.
SSA also says earnings can include:
- bonuses;
- commissions;
- vacation pay.
If you operate a business or work as an independent contractor, net self-employment income can therefore affect the earnings test.
What Income Does NOT Count?
The retirement earnings test is not based on every dollar of income that enters your household.
SSA says it generally does not count:
- pensions;
- annuities;
- investment income;
- interest;
- veterans benefits;
- other government retirement benefits;
- military retirement benefits.
For example, suppose you receive:
$20,000 in wages
plus:
$30,000 from a pension.
For purposes of the retirement earnings test, the pension itself does not cause you to exceed the earnings limit.
The wages are what matter.
This is different from federal income-tax rules.
Do IRA or 401(k) Withdrawals Count Toward the Earnings Limit?
Retirement-account withdrawals generally are not wages or net self-employment earnings.
The Social Security earnings test focuses primarily on income from working.
However, withdrawals from retirement accounts can affect:
- income taxes;
- taxation of Social Security;
- Medicare IRMAA calculations.
Those are separate rules.
Do not confuse:
Social Security earnings test
with:
Social Security income taxation.
They are completely different calculations.
Does Investment Income Count?
Generally, no.
SSA specifically states that investment income and interest do not count as earnings for the retirement earnings test.
So earning money from:
- stock dividends;
- interest;
- investment gains;
does not by itself trigger the retirement earnings test.
Again, those amounts may have tax consequences, but that is separate.
Does a Pension Count?
No, not for the retirement earnings test.
A pension is not treated as wages from current employment for this purpose.
The same is generally true of annuities.
Does Veterans Disability Compensation Count?
SSA states that veterans benefits do not count as earnings under the retirement earnings test.
Therefore, VA benefits do not by themselves push someone over the $25,560 retirement earnings limit.
What About Self-Employment?
Self-employment deserves special attention.
SSA generally counts:
net earnings from self-employment
rather than simply total business revenue.
If you own a business while collecting early retirement benefits, the amount and nature of the services you perform can also matter under Social Security’s special retirement rules.
Someone who is self-employed and considering retirement benefits before FRA should keep accurate records and review the rules directly with SSA if their circumstances are complex.
What Is the Special First-Year Retirement Rule?
There is another important exception for some people who retire during the middle of a year.
Imagine you work from January through June and earn well above the annual earnings limit.
Then you fully retire in July and begin Social Security.
Using only the annual limit could create an unfair result because most of your earnings were received before you retired.
SSA therefore has a:
special one-year earnings rule.
Under this rule, SSA can sometimes pay a full Social Security benefit for a whole month it considers you retired even if your total annual earnings exceed the standard annual limit.
This rule is commonly important during:
the first year of retirement.
SSA’s 2027 fact sheet lists a lower monthly exempt amount of:
$2,130
and a higher FRA-year monthly amount of:
$5,660.
The special monthly rule also considers substantial services performed in self-employment, so people retiring mid-year should verify the rule with SSA based on their exact circumstances.
Does the Earnings Limit Apply to Social Security Disability?
Do not use the $25,560 retirement earnings limit to decide how much you can earn while receiving Social Security Disability Insurance.
SSDI uses different work rules, including concepts such as:
- substantial gainful activity;
- trial work periods;
- work incentives.
For 2027, SSA has separate disability thresholds.
The retirement earnings test discussed in this article applies principally to retirement benefits and also has rules relevant to survivor benefits.
What About Survivor Benefits?
The retirement earnings test can also affect people receiving Social Security survivor benefits before the applicable retirement FRA used for the earnings test.
SSA notes that for purposes of the annual earnings test on survivor benefits, it uses the beneficiary’s retirement full retirement age.
Because survivor-benefit claiming rules can differ from regular retirement rules, beneficiaries receiving survivor payments should check their specific situation carefully.
For a broader explanation, see our Social Security Survivor Benefits 2027 guide.
Does the $25,560 Limit Apply to SSI?
No.
Supplemental Security Income has completely different income and resource rules.
Do not use the Social Security retirement earnings-test limit when calculating SSI eligibility.
SSI is a needs-based program.
The 2027 federal SSI maximum has also changed because of the 3.6% COLA, but its income rules are separate from the retirement earnings test.
Does Social Security Tax Still Come Out of Your Paycheck?
Yes.
Receiving Social Security retirement benefits does not automatically stop payroll taxes.
If you continue working in covered employment, you generally continue paying:
Social Security payroll tax
and:
Medicare payroll tax.
Your employer generally continues paying its share as well.
Self-employed workers generally pay the applicable self-employment taxes.
Can Working Increase Your Future Social Security Benefit?
Potentially, yes.
SSA reviews workers’ earnings records.
Social Security retirement benefits are generally calculated using your highest 35 years of indexed earnings.
If your new earnings replace a lower year in your benefit calculation, continued work can potentially increase your monthly benefit.
That is separate from the earnings test.
So it is possible for someone to have benefits temporarily withheld because of current earnings while also creating a higher future benefit through additional work.
2027 Earnings Limit vs. Social Security Taxable Maximum
These two numbers are frequently confused.
The 2027 retirement earnings limit is:
$25,560
for someone under FRA throughout the year.
The 2027 Social Security taxable maximum is:
$192,300.
They serve completely different purposes.
$25,560 earnings-test limit
Determines whether some retirement benefits may be temporarily withheld for someone claiming before FRA.
$192,300 taxable maximum
Determines how much annual earnings are subject to the Social Security portion of payroll taxes.
You can read our separate guide to the 2027 Social Security Taxable Maximum for the payroll-tax rules.
2027 Earnings Limit vs. 2027 COLA
The 2027 earnings limit and the 2027 Social Security COLA are also separate.
The official 2027 COLA is:
3.6%.
The COLA increases Social Security and SSI benefit amounts.
The retirement earnings limit determines how much someone below FRA can earn before benefit withholding begins.
A person can therefore:
receive the 3.6% COLA
and still:
have some benefits withheld because of work.
Both rules can apply at the same time.
For your new payment amount, see our 2027 Social Security COLA coverage and 2027 COLA Notice guide.
Should You Stop Working to Avoid the Earnings Test?
Not necessarily.
It can be a mistake to view the earnings test in isolation.
Suppose working gives you:
$30,000 in additional wages
but causes:
$2,220
of Social Security benefits to be withheld.
Stopping work solely to avoid the $2,220 withholding could mean giving up substantially more employment income.
Additional work can also:
- increase retirement savings;
- provide employer benefits;
- increase future Social Security benefits in some cases;
- delay withdrawals from savings.
The best decision depends on your full financial situation.
Should You Delay Social Security If You Plan to Keep Working?
That can be worth considering.
Claiming before full retirement age has two separate consequences:
- Your monthly retirement benefit is permanently reduced for claiming early.
- The earnings test may temporarily withhold benefits if you continue working above the annual limit.
Someone who is still earning a high salary may therefore decide that delaying Social Security makes more sense.
But that is not automatically the right decision for everyone.
Factors can include:
- health;
- life expectancy;
- spouse benefits;
- survivor planning;
- cash needs;
- savings;
- taxes;
- employment plans.
Full Retirement Age Becomes Especially Important in 2027
For most people born in:
1960
full retirement age is:
67.
That means many people born in 1960 will reach FRA during 2027.
For them, the special:
$67,920
limit may be especially important.
Once their FRA month arrives, the retirement earnings test ends.
Our Social Security Full Retirement Age in 2027 guide explains the age-67 rules in detail.
What If Your Earnings Change During 2027?
If you receive benefits before FRA and your earnings turn out to be different from what you previously estimated, SSA says you should report the change.
This can help prevent:
- too much benefit withholding;
- under-withholding;
- an eventual overpayment.
If SSA pays more benefits than you were entitled to receive under the earnings test, it may later seek repayment.
Keeping your earnings estimate current can therefore prevent an unpleasant surprise.
2027 Social Security Earnings Limit Calculator
For someone below FRA throughout 2027, a simple estimate is:
Step 1
Take your expected 2027 wages or net self-employment earnings.
Step 2
Subtract:
$25,560
Step 3
If the result is positive, divide it by:
2
Formula
(Earnings − $25,560) ÷ 2 = estimated benefit withholding
Example:
Expected earnings:
$45,000
Subtract limit:
$45,000 − $25,560 = $19,440
Divide by two:
$19,440 ÷ 2 = $9,720
Estimated withholding:
$9,720
If your earnings are $25,560 or below, the retirement earnings test itself produces:
$0 withholding.
Calculator for Someone Reaching FRA in 2027
If you reach FRA during 2027:
Step 1
Count only earnings before the month you reach FRA.
Step 2
Subtract:
$67,920
Step 3
Divide positive excess earnings by:
3
Formula:
(Pre-FRA earnings − $67,920) ÷ 3 = estimated withholding
Once you reach FRA:
No earnings-test withholding applies.
Frequently Asked Questions
What is the Social Security earnings limit for 2027?
The 2027 annual earnings limit is:
$25,560
for someone who remains below full retirement age throughout the year.
How much can I earn per month on Social Security in 2027?
SSA lists a monthly lower exempt amount of:
$2,130
for 2027.
The annual earnings test normally uses the $25,560 annual amount, while special monthly rules can apply in certain situations, particularly during the first year of retirement.
What is the 2027 earnings limit if I reach full retirement age?
The higher 2027 limit is:
$67,920.
Only earnings before the month you reach FRA count toward that test.
How much does Social Security take if I earn too much?
If you remain below FRA all year, SSA generally withholds:
$1 for every $2 above $25,560.
If you reach FRA during 2027, SSA generally withholds:
$1 for every $3 above $67,920
for applicable earnings before your FRA month.
Can I make $30,000 while collecting Social Security?
Yes.
If you remain below FRA throughout 2027, $30,000 is $4,440 above the $25,560 limit.
Approximate withholding:
$2,220.
Can I make $50,000 and collect Social Security?
Yes.
If you remain below FRA throughout the year, $50,000 is $24,440 over the limit.
Approximate withholding:
$12,220.
Can I earn unlimited money after full retirement age?
For purposes of the Social Security retirement earnings test:
yes.
Beginning with the month you reach FRA, there is no earnings-test limit.
Other tax rules can still apply.
Do pension payments count toward the $25,560 limit?
Generally, no.
SSA says pensions are not counted as earnings for purposes of the retirement earnings test.
Do investment gains count?
Investment income and interest generally do not count toward the retirement earnings test.
Do 401(k) withdrawals count?
Retirement-account withdrawals generally are not wages or self-employment earnings for the retirement earnings test, although they can have separate tax and Medicare consequences.
Does self-employment income count?
Yes.
SSA generally counts net earnings from self-employment.
Are benefits withheld because I work gone forever?
Not necessarily.
When you reach FRA, SSA recalculates your benefit to account for months in which benefits were withheld because of excess earnings.
Does the $25,560 limit apply to SSDI?
No.
SSDI has separate work rules and disability earnings thresholds.
Does it apply to SSI?
No.
SSI has separate income and resource rules.
What is full retirement age in 2027?
For people born in 1960 or later, full retirement age is generally:
67.
Bottom Line
The official 2027 Social Security earnings limit is $25,560 for someone who remains under full retirement age throughout the year.
If you earn more than that:
SSA generally withholds $1 in benefits for every $2 above the limit.
If you reach full retirement age during 2027, a much higher limit applies:
$67,920.
For earnings above that amount before your FRA month:
SSA generally withholds $1 for every $3 above the limit.
Beginning with the month you reach full retirement age:
there is no Social Security retirement earnings limit.
And remember:
The earnings test does not mean you are prohibited from working.
It does not count every type of income.
And benefits withheld because of excess earnings are not necessarily gone forever—SSA recalculates your monthly benefit at full retirement age to account for applicable months of withholding.
For workers collecting Social Security in 2027, the three numbers to remember are:
$25,560 is standard earnings limit
$67,920 is limit in the year you reach FRA
$0 is earnings limit after you reach FRA