Maximum Social Security Benefit in 2027: $5,358 at Age 70
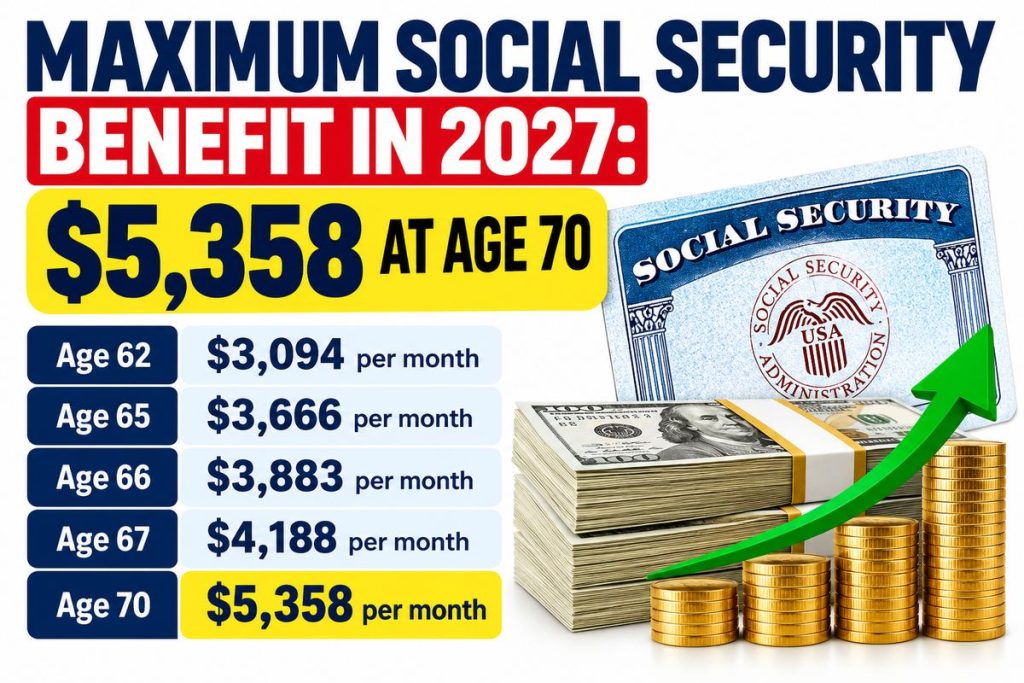
Maximum Social Security Benefit in 2027: $5,358 at Age 70
The maximum Social Security benefit in 2027 can reach $5,358 per month for a worker retiring at age 70, according to official Social Security Administration calculations.
But $5,358 is not the maximum payment available to everyone.
The amount a person can receive depends on their lifetime earnings, retirement age and the year they begin collecting benefits.
According to SSA’s official maximum-taxable benefit examples, the maximum monthly Social Security retirement benefits for workers retiring in January 2027 are:
| Retirement age | Maximum monthly benefit in 2027 | Annual equivalent |
|---|---|---|
| 62 | $3,094 | $37,128 |
| 65 | $3,666 | $43,992 |
| 66 | $3,883 | $46,596 |
| 67 | $4,188 | $50,256 |
| 70 | $5,358 | $64,296 |
The highest figure in SSA’s 2027 examples is therefore $5,358 per month at age 70, or $64,296 over 12 months before taxes, Medicare premiums or other applicable deductions.
Here’s how the maximum benefit works, who could qualify and why simply waiting until age 70 does not guarantee a $5,358 monthly check.
What Is the Maximum Social Security Benefit in 2027?
The maximum Social Security retirement benefit shown by SSA for a worker retiring at age 70 in January 2027 is:
$5,358 per month.
At age 67, the corresponding maximum is:
$4,188 per month.
At age 62 and one month, SSA’s example shows:
$3,094 per month.
These are official benefit examples for workers with exceptionally high lifetime earnings.
SSA states that the calculations assume the worker had maximum-taxable earnings since age 22.
That requirement is important because reaching age 70 alone does not qualify someone for the maximum benefit.
Maximum Social Security Benefit at Age 62 in 2027
A worker retiring at age 62 and one month in January 2027 can receive a maximum of:
$3,094 per month
under SSA’s maximum-taxable earnings example.
Over 12 months, that equals:
$3,094 × 12 = $37,128
before applicable deductions.
Age 62 is generally the earliest age at which regular Social Security retirement benefits can begin.
However, claiming before full retirement age permanently reduces the monthly retirement benefit.
For people born in 1960 or later, full retirement age is 67.
Someone with a full retirement age of 67 who starts benefits at 62 generally receives a benefit up to 30% lower than the amount payable at full retirement age.
For a detailed explanation, see our guide to Social Security full retirement age in 2027.
Maximum Social Security Benefit at Age 67 in 2027
SSA’s published maximum for a worker retiring at age 67 in January 2027 is:
$4,188 per month.
Annualized, that equals:
$4,188 × 12 = $50,256.
Age 67 is the full retirement age for people born in 1960 or later.
A person who begins benefits at their full retirement age can generally receive 100% of their calculated Primary Insurance Amount, subject to the individual’s earnings record and other applicable Social Security rules.
The $4,188 figure is also the maximum benefit for a worker retiring at full retirement age shown in SSA’s 2027 COLA fact sheet.
Maximum Social Security Benefit at Age 70 in 2027
The largest benefit in SSA’s January 2027 maximum-taxable examples is:
$5,358 per month at age 70.
That produces an annual amount of:
$5,358 × 12 = $64,296.
Waiting beyond full retirement age can increase retirement benefits through delayed retirement credits.
SSA explains that monthly retirement benefits continue increasing when an eligible worker delays benefits beyond full retirement age, but those increases stop at age 70.
You can review SSA’s official delayed-retirement information for more information about how delayed retirement affects benefits.
Does Waiting Until 70 Guarantee $5,358 Per Month?
No.
This is one of the most important points to understand about the maximum Social Security benefit in 2027.
Waiting until age 70 can increase a worker’s monthly benefit, but it does not automatically create a $5,358 payment.
Your actual Social Security retirement benefit depends primarily on your earnings history and the age at which you claim.
A worker whose lifetime earnings were well below Social Security’s annual taxable maximum will generally receive less than the maximum even if they wait until age 70.
SSA’s $5,358 example assumes maximum-taxable earnings since age 22.
That represents an unusually strong earnings history.
Why You Shouldn’t Simply Compare $4,188 With $5,358
There is another important detail that is easy to miss.
The person retiring at age 67 in January 2027 and the person retiring at age 70 in January 2027 belong to different birth cohorts.
The age-67 worker would generally have been born in 1960, while the age-70 worker would generally have been born in 1957.
That means the two examples can involve different:
birth years,
full retirement ages,
earnings-indexing periods,
benefit calculation years,
and delayed-retirement-credit periods.
Therefore, you should not assume that one individual can simply take the $4,188 maximum at age 67 and apply a fixed percentage to arrive at SSA’s $5,358 age-70 maximum.
The published figures represent separate maximum-benefit examples for workers retiring at different ages in the same calendar year.
For retirement planning, your own personalized Social Security estimate is much more useful than comparing national maximum figures.
How Do You Qualify for the Maximum Social Security Benefit?
Qualifying for the maximum Social Security benefit requires an exceptional earnings history.
SSA says its maximum-benefit examples assume workers earned at least the annual Social Security taxable maximum beginning at age 22.
Social Security retirement benefits are calculated using a worker’s earnings record.
The benefit formula generally considers the worker’s highest 35 years of indexed earnings when calculating Average Indexed Monthly Earnings, or AIME.
Lower-earning years can reduce the average.
Having fewer than 35 years of covered earnings can also reduce benefits because missing years may be represented by zeros in the calculation.
This means earning a very high salary for only a few years is normally not enough to receive the maximum retirement benefit.
What Is the 2027 Social Security Taxable Maximum?
The official 2027 Social Security taxable maximum is $192,300.
That is up from:
$184,500 in 2026.
The increase is:
$192,300 − $184,500 = $7,800.
SSA calls this amount the contribution and benefit base.
You can verify the figure through SSA’s official Contribution and Benefit Base page.
For 2027, the 6.2% employee Social Security tax applies to covered earnings up to $192,300.
An employee earning at least that amount would therefore reach a maximum employee OASDI contribution of:
$192,300 × 6.2% = $11,922.60.
An employer generally pays a matching 6.2% contribution.
The Medicare payroll tax operates differently and does not use the same $192,300 wage cap.
Does Earning $192,300 in 2027 Guarantee the Maximum Benefit?
No.
Earning $192,300 or more during 2027 means a worker has reached the Social Security taxable maximum for that year.
It does not guarantee the maximum retirement benefit.
A worker’s retirement calculation is based on many years of earnings.
Someone who earns at or above the taxable maximum in 2027 but had substantially lower earnings during earlier years may receive considerably less than the maximum monthly retirement benefit.
To match SSA’s published maximum-taxable example, the worker would need a much longer history of earnings at the applicable maximum levels.
2027 Social Security Taxable Maximum by Year
The wage base has risen substantially in recent years:
| Year | Social Security taxable maximum |
|---|---|
| 2024 | $168,600 |
| 2025 | $176,100 |
| 2026 | $184,500 |
| 2027 | $192,300 |
Earnings above the annual Social Security taxable maximum generally do not count as additional covered earnings for calculating Social Security retirement benefits for that year.
Maximum Social Security Benefit vs. Average Benefit
Most retirees receive far less than the maximum benefit.
Social Security’s official 2027 COLA fact sheet estimates the average monthly benefit for all retired workers will be approximately:
$2,170 in January 2027.
Compare that with the maximum-benefit examples:
| Benefit example | Monthly amount |
|---|---|
| Estimated average retired worker | $2,170 |
| Maximum at age 62 | $3,094 |
| Maximum at age 67 | $4,188 |
| Maximum at age 70 | $5,358 |
The gap is substantial because the maximum figures represent workers with unusually high earnings histories.
The average figure is much more representative of what typical retired workers receive.
Social Security’s official 2027 cost-of-living adjustment is 3.6%.
For more details about how the increase affects payments and program limits, read our guide to the official 2027 Social Security COLA and new payment amounts.
Does the 3.6% COLA Create the $5,358 Maximum?
Not by itself.
The 3.6% COLA increases benefits for Social Security beneficiaries, but determining the maximum benefit for a newly retiring worker involves more than multiplying a previous maximum by 1.036.
The calculation can involve:
lifetime indexed earnings,
the year the worker becomes eligible,
Primary Insurance Amount calculations,
the worker’s full retirement age,
claiming age,
delayed retirement credits,
and applicable automatic benefit increases.
That is why comparing maximum Social Security benefits from one year to another requires care.
Can a Married Couple Receive More Than $5,358?
Yes, depending on their individual eligibility.
The $5,358 amount is an individual worker example. It is not a household maximum.
If both spouses have qualifying earnings records, each spouse may receive retirement benefits based on their own work history.
A husband, wife or qualifying ex-spouse may also be eligible for a spouse benefit under certain circumstances.
However, a spouse does not automatically receive half of the worker’s age-70 payment.
Spousal benefits are generally based on the worker’s Primary Insurance Amount rather than simply taking 50% of a benefit increased by delayed retirement credits.
Our guide to Social Security spousal benefits in 2027 explains the rules in more detail.
Is $5,358 the Absolute Maximum Social Security Payment Anyone Can Receive?
It should not be interpreted as a universal maximum applying to every Social Security beneficiary in every situation.
SSA itself notes that there is no single simple maximum that describes every possible retirement benefit.
Benefits depend on factors including:
the worker’s lifetime earnings,
claiming age,
birth year,
year of retirement,
cost-of-living adjustments,
and other individual circumstances.
The $5,358 figure specifically represents SSA’s maximum-taxable earnings example for a worker retiring at age 70 in January 2027.
That distinction matters.
How Can You Estimate Your Own 2027 Social Security Benefit?
Your personalized estimate is more useful than the national maximum.
SSA allows workers to review retirement estimates based on their actual earnings records.
The agency’s benefit estimate service can show estimates at different claiming ages and allow users to see how future earnings could affect retirement payments.
You should also review your Social Security earnings record for missing or incorrect earnings because your recorded work history affects benefit calculations.
If you are already receiving benefits, you can use our Social Security COLA 2027 calculator to compare monthly benefit amounts after the 2027 adjustment.
Frequently Asked Questions
What is the maximum Social Security benefit in 2027?
SSA’s maximum-taxable earnings examples show $5,358 per month for a worker retiring at age 70 in January 2027.
What is the maximum Social Security benefit at age 62 in 2027?
The maximum example for a worker retiring at age 62 and one month in January 2027 is $3,094 per month.
What is the maximum Social Security benefit at age 67 in 2027?
SSA shows a maximum of $4,188 per month for a worker retiring at age 67 in January 2027.
What is the maximum Social Security benefit at age 70 in 2027?
The official SSA maximum-taxable earnings example is $5,358 per month.
How much is a $5,358 monthly Social Security benefit per year?
The calculation is:
$5,358 × 12 = $64,296 per year.
This is the gross annual equivalent before applicable taxes, Medicare premiums or other deductions.
What is the average Social Security retirement benefit in 2027?
SSA estimates the average monthly Social Security benefit for retired workers will be approximately $2,170 in January 2027 after the 3.6% COLA.
How much do you need to earn to get the maximum Social Security benefit?
There is no single one-year salary that guarantees the maximum benefit.
SSA’s maximum-benefit examples assume maximum-taxable earnings since age 22.
The taxable maximum is $192,300 for 2027, but reaching that amount for one year does not guarantee the maximum retirement benefit.
Will everyone who waits until age 70 receive $5,358?
No.
Waiting until 70 can increase a worker’s monthly payment through delayed retirement credits, but the final benefit still depends heavily on lifetime earnings.
Do Social Security retirement benefits keep increasing after age 70?
Delayed retirement increases stop at age 70. Waiting beyond age 70 solely to earn additional delayed retirement credits does not increase the benefit further.
Bottom Line
The maximum Social Security benefit in 2027 is $5,358 per month at age 70 under SSA’s published maximum-taxable earnings example.
The official maximum examples for workers retiring in January 2027 are:
| Retirement age | Maximum monthly benefit |
|---|---|
| 62 | $3,094 |
| 65 | $3,666 |
| 66 | $3,883 |
| 67 | $4,188 |
| 70 | $5,358 |
The age-70 maximum equals $64,296 over 12 months.
However, waiting until age 70 does not automatically qualify someone for that amount.
SSA’s maximum examples assume an exceptional lifetime earnings history with maximum-taxable earnings since age 22.
For most workers, the better question is not simply, “What is the maximum Social Security benefit?”
It is:
How much will my own earnings record provide if I claim at 62, full retirement age or 70?
Checking your personalized Social Security estimates at different claiming ages is the best way to answer that question.